Who needs the EU – Forza Italia!
Politics by ego may be the status quo in play here, especially as Chancellor Merkel (the last one standing) who continues to hold the force of the EU behind her. But will her ability to lead the German people through this time be called into question? The momentum is clearly on the side of the “identity” politics, surged by the huge influx of immigration into Europe. Italy was next to fall into limbo following the historic Brexit vote, even though people are predominantly pro-Europe. However, the key is not the common currency, but common values and the idea of both are clearly breaking down. We have seen it with Renzi today, as he struggles to come to terms with leadership.
The Trump USD Bubble, the case of the Yen.
UBS recently stated that the markets and traders alike have completely misinterpreted the Trump victory and believe that the JPY will strengthen to $98 by this time next year. This hypothesis was spear headed by the firm’s Tokyo based research team who cited expectations for fiscal expansions being overstated and how more “protection” style policies will come into play with the new Trump administration. This comes at a time where Trump’s campaign pledging “tax breaks” and more spending over the next decade, in addition to restructuring the entire US trade environment, in fact pushing to sanction firms sending jobs overseas. The markets on the whole have seen the new President elect as a further form of stimulus and this can be seen clearly in the USDJPY cross, where recently the pair reached a month high at 114 capping the biggest three week rally since 1995. It becomes very unclear when trying to analyse the reality behind Trump’s promises and how they will actually become policy. He has already backed away from the Mexico-US wall border, with 10+ nations saying it would be a disaster. This uncertainty really has helped to form FX forecasts, with Japanese analysts very much on the side of a JPY strong hold citing market cycles and market bubbles. For now, the USD still remains relatively strong, however how long could this actually continue for? – How much of a drag could this cause for US businesses’ revenue? Are we actually looking at the next USD bubble and will the markets continue to have faith in Trump’s policies?
I’ve cracked the #Brexit conundrum!
Dear Britain, Please don’t worry about your decision to leave the EU. I have a solution that should relieve both remainers and leavers equally. A moment comes, which comes but rarely, when we step from the old to the new….I’ve cracked the #Brexit conundrum! Cameron needs to immediately apply for Britain to become a Union Territory of the Republic of India. Whilst historically speaking it seems only right and proper to give India a chance to rule Britain for a few hundred years – it actually makes a lot of sense for the British too! Worried about jobs? India’s economy is growing 4x faster than Europe’s and will overtake the entire EU’s sometime in the 2030s – becoming twice the size of the EU economy by 2050. In economic terms alone every young Brit should wish to replace their garish red EU passport with a classy blue Indian one ASAP. Worried about the future of the NHS? India already provides nearly as many Doctors to the NHS as the EU does – and that doesn’t even include those of Indian origin, born or educated, in Britain. 25,055 Indian v 30,082 EU. Worried about diversity? With over 100 different languages spoken everyday and adherents of every religion – even Britain’s favourite materialist consumption – there truly is something for everyone here! Worried about being understood? English is one of India’s two official languages – which will be a huge relief for all those have struggled to communicate with their continental neighbours for all these years. Worried about not being part of something bigger? India has more than twice the population of the EU. Half of which are under 35, so the bonus is no more worries about an ageing population! Worried about where to go on holiday? The Himalayas are nearly three times the height of the Alps and thousands of miles longer – there are more sandy beaches along India’s coastline than all the Costas you can dream of – and India has tropical rainforests and even a desert too! Plenty of visa free inter-railing adventures as well on the world’s largest railway network. Worried about not being ruled by an unlected bureaucracy in a far away land? We’ve got that covered as well! Nowhere on the planet has perfected the shuffling of paper and writing of rules better than New Delhi – what’s more India’s civil servants salaries are more than 10x lower than Brussels. Talk about getting more for less! British MPs, the whole of Whitehall and even the Royal Family (subject to the return of the Kohinor) can all be pensioned off at the fast expanding and internationally renowned Best Exotic Marigold Hotel chain in Jaipur. Which would free up the Houses of Parliament, Buckingham Palace and much of Central London to become a permanent Bollywood film set. With more viewers than Hollywood this is sure to help keep London’s tourist economy going – which within a decade or two will be mostly Indians in any case. Embrace the 21st Century. Swap Brussels for Delhi. Say Goodbye to Little Europe and Namaste to Incredible India! Yours in waiting,A 3rd Generation Immigrant of British Origin,New Delhi, India🙏
#BrexitVote = A Genuine Clusterfuck!
137 billion pounds was wiped off the value of the UK stockmarket in the first nine minutes of trading. That’s the equivalent of nine years EU membership fees. The falling value of the pound will cause the cost of imports to rise, making things more expensive on the high street. The poorer parts of Britain have used the referendum as a vote on globalisation: they’ve been shafted by continuous British governments since 1979, governments who have off-shored their jobs, used immigration to lower their wages and deregulated banks to provide cheap credit to fund their consumption. None of this will change outside of the EU. The problem always was, is and will be that domestic UK politicians do not represent the interests of the traditional working class, they represent international finance. And under Johnson and Gove they still will. The UK is an international CAPITALIST economy, it needs inward investment to pay for its current account deficit (debt), which is massive. 50% of our inward investment came from the EU in 2015. Low wages – yes even with George Osborne’s supposed ‘living wage’ – help to attract this investment. Immigration is a structural part of the UK economy and this is not going to change any time soon. Even Farage said he would use migrants from the Commonwealth (lol – that basically ended in 1956 @Suez), rather than the EU. Immigration will not stop, but our economy will probably take a huge battering: The UK economy is 79% services, services are harder to trade than manufactured goods because of the fact that people are integral to services, you can’t just ship them overseas like a bag of spanners. The UK had a free ‘passport’ to trade services in the EU. The City of London (services) generates 10% of the UK’s total GDP. Roughly a quarter of the UK’s financial sector business involves the EU’s Single Market, equivalent to 2 per cent of gross domestic product. And balanced on top is a wider array of professional services. (Financial Times). Plus: developed countries buy more services than developing countries who are at a different stage in their economic development. The EU is made up of some of the richest developed countries on the planet. The entire structural configuration of our economy favours services sold to developed countries and we just risked putting the kibosh on that. Smart move. There’s more. Free trade agreements take years to negotiate, and the UK will be screaming out for FTAs to ensure trade based on best possible terms, rather than the default WTO position – yes that’s right, even on leaving the EU there are other international organisations we have to conform to, we call this the modern world – Under WTO there are 10% import tariffs on automotive manufacturing, one of the last bastions of manufacturing in the UK. Without an FTA all UK automotive exports will see a 10% tariff slapped on them. Let that sink in for a moment. A UK crying out for FTAs will give negotiating partners leverage, the UK does not have the upperhand here. And as for an EU-UK FTA, the UK is 5% of global GDP (2015), the EU 26%, who do you think will have the upperhand in those negotiations? As for us importing more from the EU than we export, we need those goods, for our standard of living and for our domestic supply chains. The fact that we import so much is not automatically something that works in our favour! Trade is not a zero sum game. And when all these British citizens fund out that they’ve been lied to over the next few years they’re going to be absolutely furious. And who do you think they will vote for then? Angry men with easy answers and tiny little moustaches maybe? I’m pretty sure it won’t be Corbyn with his mystical magical 1970s timemachine. This is a genuine clusterfuck. Cameron has risked the union of the Kingdom – Northern Ireland voted remain 56%, Scotland 62% – and the wider EU in trying to appease to racists, the angry and the ignorant. This is not the behaviour of a statesman. It is the behaviour of an opportunist and a coward. His name will go down in history as the man who accidentally broke up Britain. Hold on to your bowler hats, its about to get bumpy.
Everything’s a Buy as Central Banks Keep on Greasing Markets
Risk assets rallying even as global growth outlook worsens Markets are driven by central bank liquidity, Commerzbank says Misery is making strange bedfellows in global markets. At a time when risky assets including stocks, commodities, junk bonds andemerging-market currencies are rallying to multi-month highs, so are the havens, from gold, government bonds to the Swiss franc and the Japanese yen. No matter that the U.S. labor market is deteriorating and the World Bank has just cut its estimates for global economic growth. Investors either don’t believe the news is bad enough to kill a global recovery that’s already long in the tooth, or they’re betting that sluggishness in some of the biggest economies means central banks will stay more accommodative for longer. “Everything is being driven by high liquidity that ultimately is being provided by central banks,” Simon Quijano-Evans, chief emerging-market strategist at Commerzbank AG, Germany’s second-largest lender, said in London. “It’s an unusual situation that’s a spill over from the 2008-09 crisis. Fund managers just have cash to put to work.” For much of the time since the financial meltdown eight years ago, investors have been in the mindset that bad economic data is good news for markets. The near-zero interest-rate policies by major central banks — and negative borrowing costs in Japan and some European nations — have pushed traders to grab anything that offers yield. And every indication that the liquidity punch bowl will stay in place is greeted by markets with a cheer. Euphoric Market The latest euphoria started Friday when the U.S. job report showed America added just 38,000 jobs in May, the worst reading since 2010. That has eliminated any chance that Federal Reserve policy makers will raise interest rate from as high as 0.5 percent, when they convene next week, according to data compiled by Bloomberg based on Fed fund futures. The odds for a move in July have declined to 20 percent, from 53 percent a week earlier. China, which contributes the most to global economic growth along with the U.S., has played its part to buoy the sentiment. The economy has stabilized following a new dose of credit expansion from earlier this year. In the euro-zone, the European Central Bank entered new territory in its effort to stimulate the flagging economy, buying the debt of some of the continent’s biggest companies for the first time. Relieved Traders By Wednesday this week, the Standard & Poor’s 500 Index reached a 10-month high, commodity prices jumped to the strongest since October and non-investment-grade bonds extended this year’s advance to more than 9 percent. The pared expectations for Fed rate hikes have also pushed the dollar lower, helping boost assets sensitive to the greenback, such as gold, oil, the yen and franc. Investors can be forgiven for feeling a sense of relief. Signs are everywhere that the U.S. economic recovery, which started seven years ago, is maturing. Earnings growth has plateaued. Business spending has sagged and global trade remains stagnant. On Tuesday, the World Bank cut its outlook for global growth this year to 2.4 percent, down from the 2.9 percent estimated in January. In the U.K., a narrowing of polls over the past week has raised the likelihood of a British exit from the European Union. Against all this, preemptive Fed rate increases would be a body blow. “There was a lot of nervousness in the markets with respect to the Fed,” said Manish Singh, who oversees about $2 billion as Crossbridge Capital’s head of investments in London. “The Fed and U.S. dollar are definitely the big factors — the fact that the Fed is not raising comes as a relief.” Exotic Corners One consequence of the concerted gains is that investors will find it more difficult to protect themselves in a market selloff, according to Goldman Sachs Group Inc. Higher correlations between regional markets make it difficult to hide out in foreign stocks. Bond yields hover near record lows, squashed by central banks’ quantitative easing plans, and defensive equities have been bid up, Goldman’s Christian Mueller-Glissman wrote in a note to clients Wednesday. That and dovish central bank policy have chased investors into exotic corners of the market looking to hedge, said Michael Purves, chief global strategist at Weeden & Co LP in Greenwich, Connecticut. “There’s a lot of rationale getting long the VIX right now,” Purves said. “It’s one way of hedging, and that argument applies anytime we get some sort of follow-through rally and volatility is low.” Shares outstanding in exchange-traded notes betting on an increase in the VIX are at all-time highs. The counts, which rise along with demand for ETFs, has nearly quadrupled over the past three months for the VelocityShares Daily 2x VIX Short Term ETN, a security that appreciates as turbulence increases and often used as an equity hedge. Short interest on the security, while still well above its historic average, has fallen 60 percent since March. “I am not entirely convinced by this rally,” said Francois Savary, who helps oversee the equivalent of $2.7 billion as chief investment officer at Prime Partners in Geneva. “There is too much correlation between asset classes and that’s dangerous when sentiment remains erratic.” Source : Bloomberg
Gold Shines In 2016!
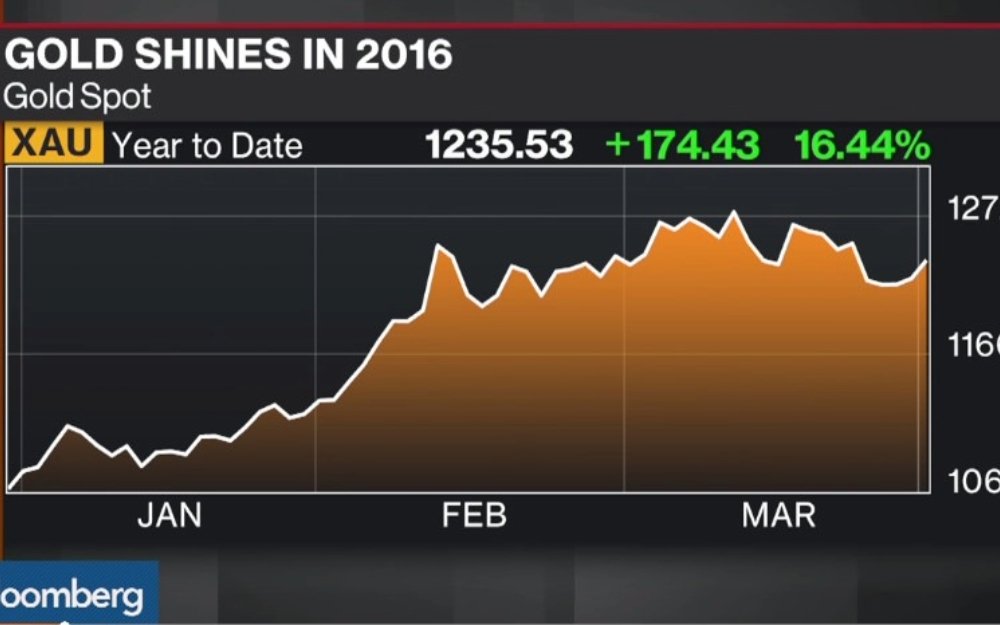
Ladies and Gentlemen, Gold has rallied almost 17% this year and most analysts are looking at the Metals markets heading higher, spear headed by the Yellow Metal. So what has been the key driver of Gold this year? Well, Monetary Policy in US. If we look back at last year one of the reason Gold struggle to rally is because it was cautious about the rate hike. This year, the drivers have changed. Looking at the Financial Market & Global Economy as a whole. After last months FED meeting we saw Gold getting a lift, upon the cautious dovish notes. We also saw that China Gold imports were lower recently and heavy restocking, especially ahead of the New Year (Jan – heading into February). So what is the cap then on the upside? Well, as Gold prices rally quickly the downside range can also be greater. Hence why if we saw a huge spike up to $1300 it could be bad for the market. However, if we see prices correcting at these levels (as well as the physical market adjusting) and the market coming into the right support – this could provide for a much more sustained move higher. Another interesting market… Platinum. Platinum flirting with 1,000 per ounce, after a 5 year pressured market and that has not been enough to lift prices at all. The underlying stocks have also been quite high with supply growing also. However, 2016 looks like the year we will see XPTUSD start to base around the 1,000 per ounce mark and prices should be lifted from here. There is also a strong fundamental reasoning for this sustained move higher. Firstly, South Africa (accounting for 80% of the World’s Platinum) and their wage negotiations, which will be very significant. From this, we should see more producer discipline and cut backs in supply growth, this should lift in investor sentiment. Most of the Rand volatility should also support this wage case. Secondly, the Jewelry market – which was incredibly weak last year.. although the price elasticity has come back into play this year offering a greater floor for prices. As always. Trade Smarter Anish8FX@Atom8.com
CALLS FROM THE TRADING FLOOR – Hold Gold Longs in 2016!
CALLS FROM THE TRADING FLOOR – BUY GOLD! Ladies & Gentlemen After a four-year slide, the price of Gold has nowhere to go but higher and many investors are starting to agree. The case for the “safe-haven” was further assured today, as China’s manufacturing data showed a contraction. For the majority of the Commodity markets, January was another bad month in a long bear-market cycle – apart from Gold. Gold rallied 5% in Jan, the best monthly gain in a year. Turmoil in Chinese markets (with the view of a potential Global Sell-Off), Oil price uncertainties and a slowing US growth has tickled Investors demand for the traditional safe-haven asset. Again, their remains a high chance the FED will hold off on further interest rate rises this year adds to the attraction for the yellow metal. There is really no sign of a re-surge in inflation and this has also been a large factor to Golds rise and this relationship goes back to the 1980’s. However, what is interesting is that through the last 12 month Gold slide, we have had China, Russia and India continuing to purchase Gold (about 55% more in 2015) – but then why did not this affect the Price? It seems investors are more focused on Financial Assets & The state of the US Economy rather than Countries Gold holdings. James Cordier, CEO of a US based Options firm said “With stock markets looking to crash all over the worlds and the US economy growing slowly, nothing is pointing to rate hikes and that is why Gold will continue to rally” . However, as mentioned in posts prior – it is important to note that Gold does not pay a coupon like other competing assets, although the price elasticity (over the last 5 years) seems to have drawn Investors (especially Central Banks, like China, Russia and India) towards the Bullion. For the coming weeks, months / Central bankers like Kuroda and Draghi have key speeches scheduled (as well as NFP this week) which could further spur the rally in Gold as the consensus is for further tightening and talks of Negative interest rates and more uncertainty. As always, Trade Smarter Anish @Anish8Fx
What To Expect With Oil At $20?
What To Expect At $20 Oil? Ladies and Gentlemen As we saw Oil dip below $30 per barrel yesterday, we have seen somewhat of an overnight reprieve in the Oil trading sessions of Asia and Europe. However, it is very hard to find reasons to be optimistic in current conditions, especially with the over-supply and concerns about China growth. The pain low Oil prices has so far caused for Oil investors and Oil producing countries may just be a taste of things to come as we head to $20 per barrel. We are now confronting $20 Oil and the likelihood is fairly great. Clearly Oil markets cannot maintain these prices (below $30) for very long and the question is for how much longer? The Gulf Economies as well as other Oil producing countries are suffering immensely, such as Malaysia – who are losing $68 million for every $1 decline in the price of Oil. Oil producers too.. EconocoPhillips – losing $2 billion for ever $10 decline and yesterday Petrobras announcing it is lopping $30 billion of it’s 5-year spending plan… Hours late, BP announces that they would slash 4,000 jobs. If there is some sort of optimistic note to leave you on and that was last year China (2nd largest consumer of Oil) imported a record amount of Crude, but that was simply taking advantage of low prices… and if/when prices go up they can start taking advantage of their huge stockpiles. $20 oil just acts to dig an even deeper hole from where you need to be before the markets look to open up again! Best of luck guys! Anish8FX @Atom8.com
Oil Crisis? Should We Now Buy Gold?
Oil Crisis? Should We Now Buy Gold? Ladies and Gentlemen With a 17% fall in Oil since the start of 2016, the possibility of $20 oil becomes a real target for Investors, as we see major Hedge Funds exit the commodity. Gold since August has been swung around in a tug of war, with Chinese equities on one side and a strong USD on the other. This pendulum has been relentless in the recent months, however with new lows in Oil prices, Gold continues to hold well in retaining it’s safe haven status.Gold has climbed 3.4% already in 2016 and investors risk aversion does not seem to be letting up. Geopolitical tensions persist in the Middle East and North Korea, as well as concerns about China’s growth forecasts. However, with a persistent strength in the USD forecasted for 2016, some analysts still call for sub $1,000 (per oz) Gold… as a “Competition for Gold” increases. With Oil prices reeling from oversupply and Gold getting a small boost, Brent crude is now at the cheapest relative price in almost a generation. But what is a “Safe-Haven”? By Economic definition (as pointed out by James Steel, of HSBC) The Safe-haven inspired demand for Gold (and other precious metals) rests on the interconnection between the state of the Gold Market and the Financial Markets of countries with long-term structural arguments for Gold accumulation (i.e. China and India) – and with this being said, HSBC forecast average Gold prices of $1,205 this year. Mr Steel is looking more with a long-term view, as accumulations continue to rise. We always tend to think about Gold being a hedge on safety, however recently Gold has been more about uncertainty and a reflection of anxiety. Gold in a deflationary environment, may actually be likely to continue it’s slide down. 2016 could well be the story of Central Bank delivery, especially as we are now risk-off as we strength in the Yen for example… but we hear nothing about the BOJ pushing back.So Is Gold still a mark of uncertainty? Well the recent shocks coming from China did Send Gold immediately higher, which is reassuring to see. I personally am long Gold, as I think it’s safe-haven status will be the trend for 2016 but in the short-term we may remain bearish. I wish you all the best of luck with your Metals trading and as we all stay tuned to this theater of events in the World markets, I wish you safer trading. Anish8Fx @ Atom8.com
The Future Is Bright – The Future Is Silver
The Future Is Bright – The Future Is Silver! Ladies & Gentlemen, As we tick closer to “Lift-Off” from the FED, the Precious Metals continue to remain cursed by the USD bulls. But what will happen after the initial FED fiasco? Will the Markets quickly learn to appreciate reality of US Debt? Will investors flock into the Metals?… I’m not too sure, but I do make a good case to stay long Silver (XAGUSD) for the next 5-10 years. Commissioned from Mr. Hague (SocGen), he has created a propriety model on measuring a move in the commodities in relation to Macro factors, the Strength of the USD, Interest Rates & Market Fundamental (Variables) & from his analysis, it is clear that Fundamentals have taken a back-seat over the past 12 months. The Macro variables are the driving force behind the Markets, covering the environment for Risk Attitude, the Volatility Index & Equities…. This is what (according to Mr. Hague) is moving Silver (chart below): Over the past 2-3 years, Silver has been trading more like Gold & recent moves have been primarily driven by the strong USD and all-round been a strong head-wind for the Metals. With Silver being 60% Demand driven, more for Industrial uses (mainly Electronics).. we begin to see Silver evolve from a Precious Metal to a Base Metal. The long-term outlook for Silver is bright, and a big part could be due to the anticipated exponential use of Solar. According to the IEA’s growth forecasts (on a mass scale) over the next 5-years, they would be using nearly 1 Billion ounces of Silver! This bodes very well for Investors looking at today’s chart, as you finally have (after 12-13 years) Silver Supply declining, especially when you think about the 2011 peak. The longer term Demand sets to pick up and it looks to be setting itself up for a Constructive move. Silver is absolutely everywhere! In your computers, in your phones… & as Emerging Market demand picks up over the next 10 years for Electronics, only naturally should this Market increase in value. So Anish, how do you see the Market shaping for the end of the year?… Well there is not much left for this year as we remain merciful to the FED’s hiking plans but I do expect Fundamentals adding more promise to the Metals market in the Longer term & hope to prove the doubters wrong, as I am personally a big fan of Silver. Best of Luck Anish8FX @ Atom8.Com