The Commodity Bloodbath
The Commodity Bloodbath Ladies & Gentlemen, As we begin to make sense of the shocking lows in Commodities across the board, we must turn our eyes onto the Macro picture to find reasoning for the short-term and also look to consider the worst-cases for the coming years. The “Demand-Destruction” story begins in China. The Chinese Economy is slowing down and the demand for commodities forming from the Chinese manufacturing sector is also on it’s way down south – with the fall led by Material/Energy companies in the Asia Pacific (falling this year circa 13%). This Market slump has shown the World how strong the in-elasticity of demand on price from China actually is. Key Chart 1 Copper is trading at 6-year lows (chart below) & Nickel (the biggest loser on the LME) is at 12-year lows. Key Chart 2 $BHP & $RIO all fell yesterday to 10-year lows as producers continued to slump across the global equities amid the bloodbath. $BHP is now looking at the prospect of having its credit rating downgraded in the next 12 months in response to further possible falls in Iron Ore & Oil prices. Another major reason behind the Commodity-glut is due to the Market concerns about further USD strength, starting with the first hike in December. Countries who do not use the USD as their primary currency will feel further heat as their currency begins to weaken amid prospective USD rallies. This will then make is cheaper to produce and create further over-supplies!Will OPEC do anything about the Over-Supply in Oil? Well, further to comments made by the Saudi’s yesterday – they are keen to work with other OPEC countries in stabilizing the market – however the facts remain & there is no quick fix! We will find out more on Dec 4th, when the OPEC heads all get together…. Meanwhile, the Glut continues as people talk about the biggest decline since the fall of the Soviet Union.Can we really find a bottom?.. Let’s take it back a notch. If we look at some charts, we can see stability over the last few weeks. and it is important to remember that the Commodity business is extremely cash intensive and producers will not be looking to cut supply but rather costs. Major Commodity producers still need the revenue. I personally think, the actual effect of this fall will truly depend on how fast the US Economy can accelerate & how long the FED Rate Hike cycle will last for. Take out your 3D Glasses and watch the rest of 2015 unfold. Best of luck Anish8FX @Atom8.com www.atom8.com
How To Make A Camel Vomit Gold
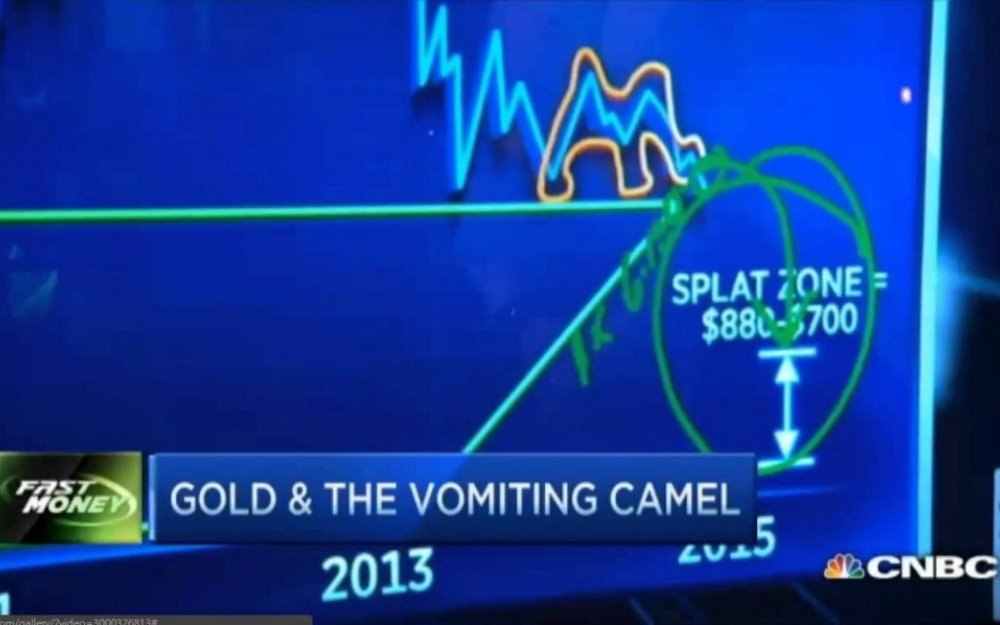
How To Make A Camel Vomit Gold Ladies and Gentlemen, Has Gold lost it’s shine? Gold traded near a 5-year low as investors continued to short bullion-backed equities pricing in expectations for the US to increase interest rates this year, further Rusting the Metals Market. Gold is heading for a thirds year on year decline as investors now brace themselves for a first interest rate increase since 2006 and according to the “theory” – Higher Rates = Less competitive metals. But Why? It is simple, as the Metals offer no dividend, hence investors naturally flock to other assets that pay interest or offer dividends. Can we head below $1000? What is now known as the “Vomiting Camel” (from the formation of the two humps [yearly highs]) – we now have the camel resting on a rhombus, indicating that a break below current levels = free-fall! The Splat Zone indicated on the char signals towards the $700-$800 for possible areas that Gold could fall into post December hikes. But what about Central Banks, The Russians & Chinese – are they still buying? – Yes!Gold purchasing (And Demand) is at record highs, as both Russia and China still maintain a policy to hedge against their currency & they will probably remain net buyers. China for example, added an extra 14 tons in October. So what happened to Economics? Well, we have to remember that XAU is backed by the USD and experts point to a “Bear-Market” cycle driven by the FED. But in my view, if we do see a hit of $700-$800 we could see a spark in the bulls. Absolutely a fascinating time to be watching the markets. Trade Smarter, Anish8FX@Atom8.com
Will 2016 Mark The Fall Of The #EmergingMarkets?
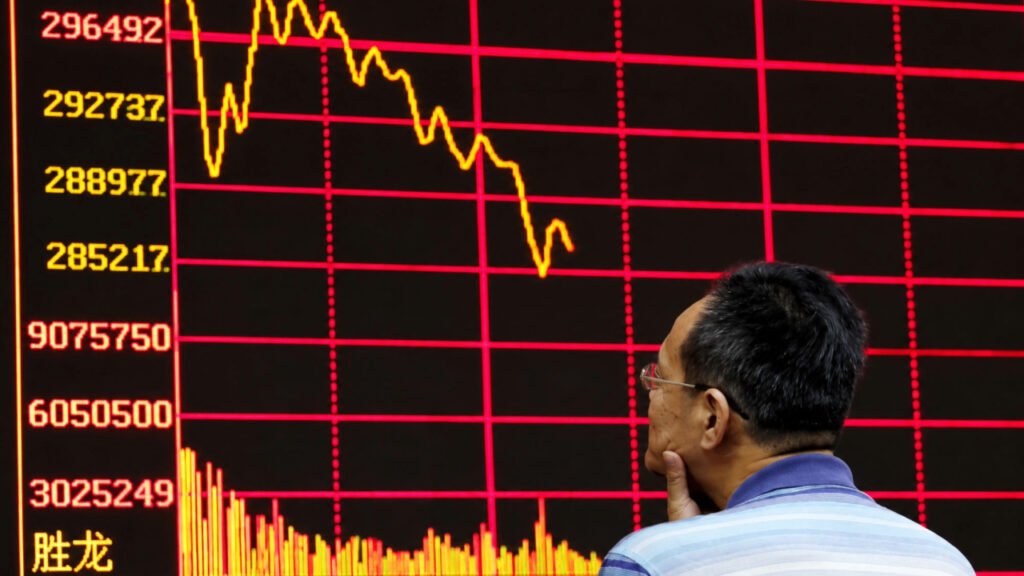
Brace yourself for a complete change in dynamics for 2016 and of course, the FED hiking cycle will become the catalyst. So should I still stay long the USD in 2016? Well in theory – Yes! In practice however, as the FED raises interest rates the USD will strengthen but these persistent increases (during the proposed cycle) will worry investors – especially for companies with Overseas Investment & for Industrial corporates (with the continued decline of commodities). It could be very expensive! A stronger USD now becomes a touchy situation. Mainly because the majority of Emerging Market Countries hold USD debt and this puts a stranglehold on the USD rallies. The probabilities of larger outflows from Countries like China, India is likely and will be the epicentre of pressure. It will be interesting to see how these Push/Pull Economic factors react next year.. Will it help their continued debt? The stage for 2016 has been set. China is an almost perfect author to this story. With recent trade numbers declining (6.9% yoy) and a staggering 18.8% decline in imports – Other Asian nations who once so heavily relied on China could now look elsewhere. As the commodity boom slows, the GDP growth required for China to maintain its growth pattern could also fall off the charts! Instead we see a Global Deflationary Threat. How will the USD react to each FED Rate Hike? – Looking at the past 11 Rate Cycles and in particular more recently when the FED moved from neutral to tightening, the USD fell 7% and to tell the way the USD could react now – one would have to look at the yield curves. Whenever it has been steep (and right now it is steep) it falls over double digits! But again, that would also depend on the forecasted tightening cycle… but really how long could it be? What about the Equity Markets? You want to be really focusing on Industrial, Tech & Energy stocks, because they will benefit from the inflationary cycle of the US Economy. But really does the public trust equities anymore? There are currently huge disparities in the major US indexes as during the past 5 years the Public have not really put any money into the equities, it has all been primarily driven by the FED & a lot of these position builders could effectively price in the first hike. Next stop… December 17. Trade Smarter! Read more: http://www.marketstoday.net/analysis/Analysis-Commentary/will-2016-mark-the-fall-of-the-emerging-markets/12906/en/#ixzz3r6u5toh4Follow us: @marketstodayme on Twitter | marketstoday on Facebook
How Do I Trade The FED Rate Hikes?
What Can I Trade When The FED Hike Rates? Ladies and Gentlemen, After a surge in Bitcoin prices, more doubts grow about the stability & long-term value of the USD. Many Economists & Analysts believe the USD to be heavily over-valued & have been calling a reversal in the USD for over 2 years now, but the brute force that is QE has only but stood in the way of purists. Figure : DXY over last 2 years Let’s first turn our eyes to the Euro and as it currently hovers around the 1.10 mark, as the FED breathes more clarity over the coming months (heading into early 2016) – many Traders are calling for 1.15-1.16 as the “Fair-Value Equilibrium”. However, until then we could still stay on the weaker side of 1.10, as Draghi continues to seemingly over-deliver on expectations… But could we really go to parity or lower? – To be honest, there is nothing magic here! When you throw in lots of numbers, taking into account coherent Econometric studies (interest rate differentials, relative to the size of the Eurozone’s balance sheets) – you can’t really go near numbers close to parity. What about the FED? The FED has a mandate which is not related to the FX Marketwhatsoever, and this is one of the main arguments from more sophisticated FX watchers (in the short-run at least). Since the first Quarter of this year, the rates market has remained completely flat but the USD has only but rocketed (more so since April)… The main question beckons.. Will the FED pull the trigger in December or not? If yes, it would only be by 25 basis points & would that really cause a huge impact?.. I don’t think so. Reality Check again! The USD is overvalued and what the FX Trader should be wary of is the Hiking Cycle that the FED will signal. In order to really justify the USD at current levels, they would need to plot an aggressive hiking path. We could actually see another 150-175 basis points over the next few years…. & that would really hurt! Again, this depends on a variety of Domestic/External factors.. (as well as the price of Oil).. A difficult one to predict now. So what do I trade? Well I would look at Cable. The Market expectations are that the BOE are maybe 9-12 months away for changing pricing, and if you compare this to the FED/ECB outlook, the“time-gap” is extremely stretched. If you look back in time, since the inception of the Bank Of England as n independent Central Bank, there has never been such a significantly wide time gap between movements in the FED to a change in the BOE. Two things to look at here, the Fundamentals & what the Market has already priced in. I do believe (as per the graph above) 1.70 to be fair value for £/$. Looking at the Markets Carney has a responsibility for bringing the market back in and delivering on his mandate. He sees risk moving way too much against him and the Market seems to remain complacent.End of the day! USD is over-valued and has been for many months. Look at Cable & it should be grinding higher and the main view on USD is that the over-evaluation will also slowly cause other Central Banks to ease of. Best of luck Anish8FX @ Atom8.Com
The Saudi Spending Phenomenon – Will It Ever Stop?
The Saudi Spending Phenomenon – Will It Ever Stop? Ladies & Gentlemen, All Market eyes have been eyeing up Oil Prices, some are calling a further slump in 2016 and others are a bit more optimistic (seeking the $50 mark). However, with these lower prices, how has the World’s biggest Oil player reacted & will it really hurt the Saudi Economy? You would of actually never of guessed there to be an Oil slump from the shine of the Saudi economy and that is no accident, it is Saudi (well-planned) policies in action. The wealth from the Oil revenues has been shared and the public have firmly supported the Al Saud family, even as turmoil beckons on the horizon. The IMF predicts that within 5 years, the Kingdom will run out of Financial Assets… But is that really true (raised eyebrow)? In theory, if they continue to spend at the rate they are & Oil prices remain low, then yes! However, they currently stand at a (Positive) 100% net cash : GDP ratio & if you look at a Country like Japan, who’s net:GDP is -200%, I begin to differ with the IMF. Saudi literally are operating with no debt. figure : Bloomberg source Can this be protected for the Future? What if Oil prices continue to fall? I think you will start to see Saudi Arabia slowly decrease their heavy military contracts & begin opening their Economy up to foreign investment, by way of issuing Government debt or opening investment into Saudi stocks. More recently, the Saudi government to pull in about $70bn from Equity markets to begin adding more liquidity within their own markets – “Welcome world to the Tadawul”. We could also see (like Qatar) a higher increase in Western Property purchases… Again another indication for potentially more spending. Saudi issuing Debt? Really? How friendly would that be? Honestly speaking (ok – be careful here Anish #whips…) The country has been caged about opening it’s Markets to the World and if done, would be extremely gradual, as they drift away from traditions. Most Governments generally support their Economy, by way of tax receipts.However, over the past 3-4 decades, Saudi has been funded with Oil receipts Reality Check.. Oil still costs $3 to get out of the ground and with current production levels, Saudi are still generating $300-400bn from Oil revenues alone (at least)! It looks like the Saudi powerhouse is only going to get stronger, especially as Investors from around Asia flock in. The next 5-10 years will be critical for the Kingdom, to really impose its strength as the World’s largest Economy, alongside China. Trade Smarter & Best of Luck for the week ahead. Best wishesAnish @ Atom8FX
Kuroda’s Economic Armageddon
Kuroda’s Economic Armageddon Ladies & Gentlemen All market eyes will be focused on Japan tomorrow, as they release updated inflation forecasts. Essentially, this is an indicator of when, or if, the bank;s board members see Japan reaching their inflation target of 2% and markets are expecting the BOJ to become even more engaged in search of the 2%. The Markets over the past few weeks have priced in more stimulus, especially with the recent Nikkei gains. Kuroda has done an excellent job in albeit trying circumstances, elevating inflation expectations in an economy that has had actually 0 inflation in the last 20 years. Just cast your mind back to 2 years ago when the USDJPY was trading around 80 and now trading around 120 & Nikkei at 8,000 & now nearly 20,000 – really putting QE into Economic action – essentially reflating the risk/assets base. But still have a lot more positive inflation to go up to 2%. However, could we really see the BOJ wanting to weaken the Yen further? At the moment Japan is still very cheap & the major corporates have been rubbing their hands in Green for the past few years now – on the flip/side the small/medium companies have been feeling the pinch with greater import costs. In addition, policy markers are also adjusting for (and looking forward to) lower a base of lower oil prices, but again adding more stimulus could be more problematic in the longer term. In my view, the decision tomorrow is more likely to be felt within the Equity Markets as Kuroda focuses on building a significant amount of more wealth into the Nikkei and their is a high conviction level from traders that something will happen – Especially as Japan owns more than half of the nations ETFs (An important Abenomics Battleground) – But really where does true Economic Theory come into play here? Central Banks buying up ETFs to promote more “risk-taking activity in the Economy”… Overall, Japan has a very important lesson that they have probably been mislearning and it’s underlying issues could be 1 of 2 things… either Deflation or is it because they failed to act like the US did in the 90s. As Buffet once said“We are all Market Vigilantes” So what is the end game for the BOJ? Does AbeNomics fail trying to approach a 2% target that they may not ever hit. We face an absolute Economic Armageddon. In my view, a lot of Japanese pride on the line. Keep your eyes peeled & fingers on the right side of the trigger! Best of luckAnish @ Atom8.com
Could Monetary Policy Divergence cause EURUSD to hit parity by December?
Could Monetary Policy Divergence cause EURUSD to hit parity by December? Ladies & Gentlemen, We have heard it over and over again & now it is crunch time, where Economic theories come into practice and the Markets click to the tune of the Central Bank Announcements. Here is what ING predicted at the start of 2015 and low & behold how the year has turned out to map the below Over the last 12 months the Markets have remained bearish and the EURUSD has fallen from 1.40 to 1.05.. but why? And the concept is pretty simple to understand, as the FED stop QE at the same time of the ECB continuing their QE policies. This is known in the Markets as a “Divergence in Monetary Policy” and as the Markets price in their expectations of a FED non-hike, the divergence is set to continue… Implicating parity and if not parity, then sub 1.00. Vamvakidis, head of G10 Strategy at Bank Of America calls for EURUSD to hit parity by December 15 and also the USDJPY to hit 125. What needs to happen for EUR parity? Well, in order for this prediction to hold – the divergence needs to move further. If we get more QE by the ECB in December and the FED does not hike (which is very ikely) we could easily see parity. But the FED hike is a matter of time and could be as early as Jan 2016. The equilibrium of the EURUSD cross is around 1.15, however, the Euro zone still has a significantly large Output Gap compared to the US & if the ECB announces an “open ended” (or Infinity based QE) – that could stir up a recipe for disaster – as the Bears would then look to push down to 0.75. How do I trade these markets? Volatility remains high and it is mainly the bears driving the markets, supported by the facts pushed from Central Bank data this month. Looking at the bigger picture, the FED will eventually look to hike rates but more than likely, it will not be until next year – even though Domestic data has improved in the US, I would not expect anything significant this week. Keep your eyes on the data A balance between Domestic Developments & External Developments is key for the FEDs decision & once we do see the hike… the bad news will hit hard & remain bad news! Can I Jump on The Karoda Vs Draghi Trade?The international expectation is for more BOJ easing and if you look at the currently inflation rate in Japan, the BOJ should actually be doing more. The USDJPY currently is not that strong, either not that weak. However, it would be ideal to remain long the volatility as no matter what happens USDJPY will move! I wish you the best of luck with your Trades & hope you keep your fingers on the right side of your mouse triggers! Anish @ Atom8.com
The Vicious Downward Cycle of Oil
Ladies & Gentlemen Oil once more trades at a near 2-month low and as vicious as it has been, the oil price collapsing cycle does not look to be over just yet. However, large institutions and Central Banks further seek a longer period of stability, especially in the eyes of the Bond Markets. The US are still heavily over-supplied and refineries continue to close down, due to mounting costs from a alack of productivity. The big players are still looking at holding sub $50 and hedging their risk with the Futures Markets… These “players” may be the ones the Central Banks turn to in the near future to assist in the un-cuffing of this downward spiral. OPEC have been heavily pressured by Venezuela (Country with the World’s largest known Oil reserves) to do something about the Oil price and have been supported by one of Africa’s biggest Oil producer, Algeria. Contrary to views from the Gulf who are welcoming the lower prices, seeing it as a chance to reform & these contrast of views continue to bear onto a larger Geo-Political issue. But how big is this issue? Saudi Arabia, the world’s largest Oil mover has been doing things recently, that in the last 30 years have been unimaginable ;1. Withdrawing money from overseas;2. Delaying contract payments; and3. Taxing lands. So how does the Market quantify these issues?.. Let’s pause for a second and cast our mind backs to mid 2007 when the Oil price hit $145.00 per barrel and the Gulf generated more money that they knew what to do with & the fact remains that Saudi’s Debt:GDP ratio is still less than 2% and in the next 10 years is estimated to stay below 7%… The main Gulf states could actually live comfortably for several years from these revenues built. So contrary to the “Geo-Politics” – Investors are more focused on the supply-side issues and may be more keen to ignore the political nature surrounding the MENA regions. Storage is still reaching tank-tops and if this trend continues, we may see for the first time in 20 years – oil investments declining for two consecutive years and this may be an indication for future oil markets.. as they look to continue their downward spiral. Optimists still seek a bottoming level – looking at Iran supplies for next year to help boost $60+ for 2017 (perhaps a fascinating new dynamic for the near future), however the fundamentalists outlook is further lower to find a strong re balance in the market. Best of luck Anish
Calls in from the Trading Floor – Hold your Oil Shorts!
“Hold your Oil Shorts” Calls from the Floor Ladies & Gentlemen As our eyes turn to the weekend – the volatile weekly Oil market draws to a close after a neat 10% slide on the back of further global supply gluts. From my post labelled “Crude Oil – A Bargain Hunt” the larger oil producing nations are looking at the $50 mark as the benchmark heading into 2016. However, the institutions & techies are looking at $50 as a perfect opportunity to remain short. So how are the Traders actually clicking? Well.. the more short-term clickers are looking at more downside targets, however some trading puritans would argue about the risk:retun. Although, as i Look at the chart & price action this morning, you can see that the market is heavily gripped by short covers. Hence the phrase “if I can scoop a small profit I will take my money and run” in my original post. Looking at a first target of $46.90 and would target ever 5 cent fall beneath this level. Tempted to leave this short open for the rest of the day heading into early next week – especially after 4 days of straight decline. WTI is set to make its steepest weekly loss in 10 weeks and Brent in 8 weeks. The Market is expected to remain heavily over-supplied heading into 2016 & sadly for the Oil companies – The Facts do not lie! Some Oil optimists are hoping that Shale production forecasts are on the decline, as output is geared towards a fall in November and also data from the EIA showed gasoline stocks falling by 2.6 mio barrels per week. Best of luck with your positions AnishFX @ Atom8.com
Gold : A Mastermind of the “Break-Out” – $1300 by 2016?
Gold : A Mastermind of the “Break-Out” – $1300 by 2016? Ladies and Gentlemen The precious yellow metal is back in the spot light after forming a pretty dull range so far this year between $1200.00 / $1100.00 and the outlook has remained bearish. However, this has all changed in the past few days as the October Bull awakens to the more uncertain Economic landscape, especially breathing from the US & from increased Geo-political action (The Ruski’s in particular)! Gold (XAUUSD.v) is showing strength above 1170 (formed yesterday) and all my indicators are pointing towards a further bull offensive. The commodity must continue to trade & hold above it’s broker resistance (turned support) at 1170 to really create more scope for strength heading into the final months of 2016. On the other click, if you remain a bear in this market – support comes in more at the 1165 level, where a break down to 1150.00 will really slam the brakes again on the metal. Me personally, I am hoping for a break of 1200 as I really do miss the days of huge Gold daily volume. fig: Atom8 MT4 Terminal How high could we go? After breaking a “key resistance” level, the investor sentiment is more positive and will probably attempt to push it to a high for year-end. Gold is now trading above it’s 200-day MA for the first time since May & prices could be further buoyed by (what is now expected to be) weaker US data & that the FED are now looking to raise rates next year. A call for above 1200.00 could be realistic by December and I would not be surprised if we even saw a move to the $1,300 mark – as volume for Metals expect to be double by next year (source : mining.com). Best of luck Traders, Anish @ Atom8.com